




Paragraph 1: The Collapse of an $18 Billion Ambition
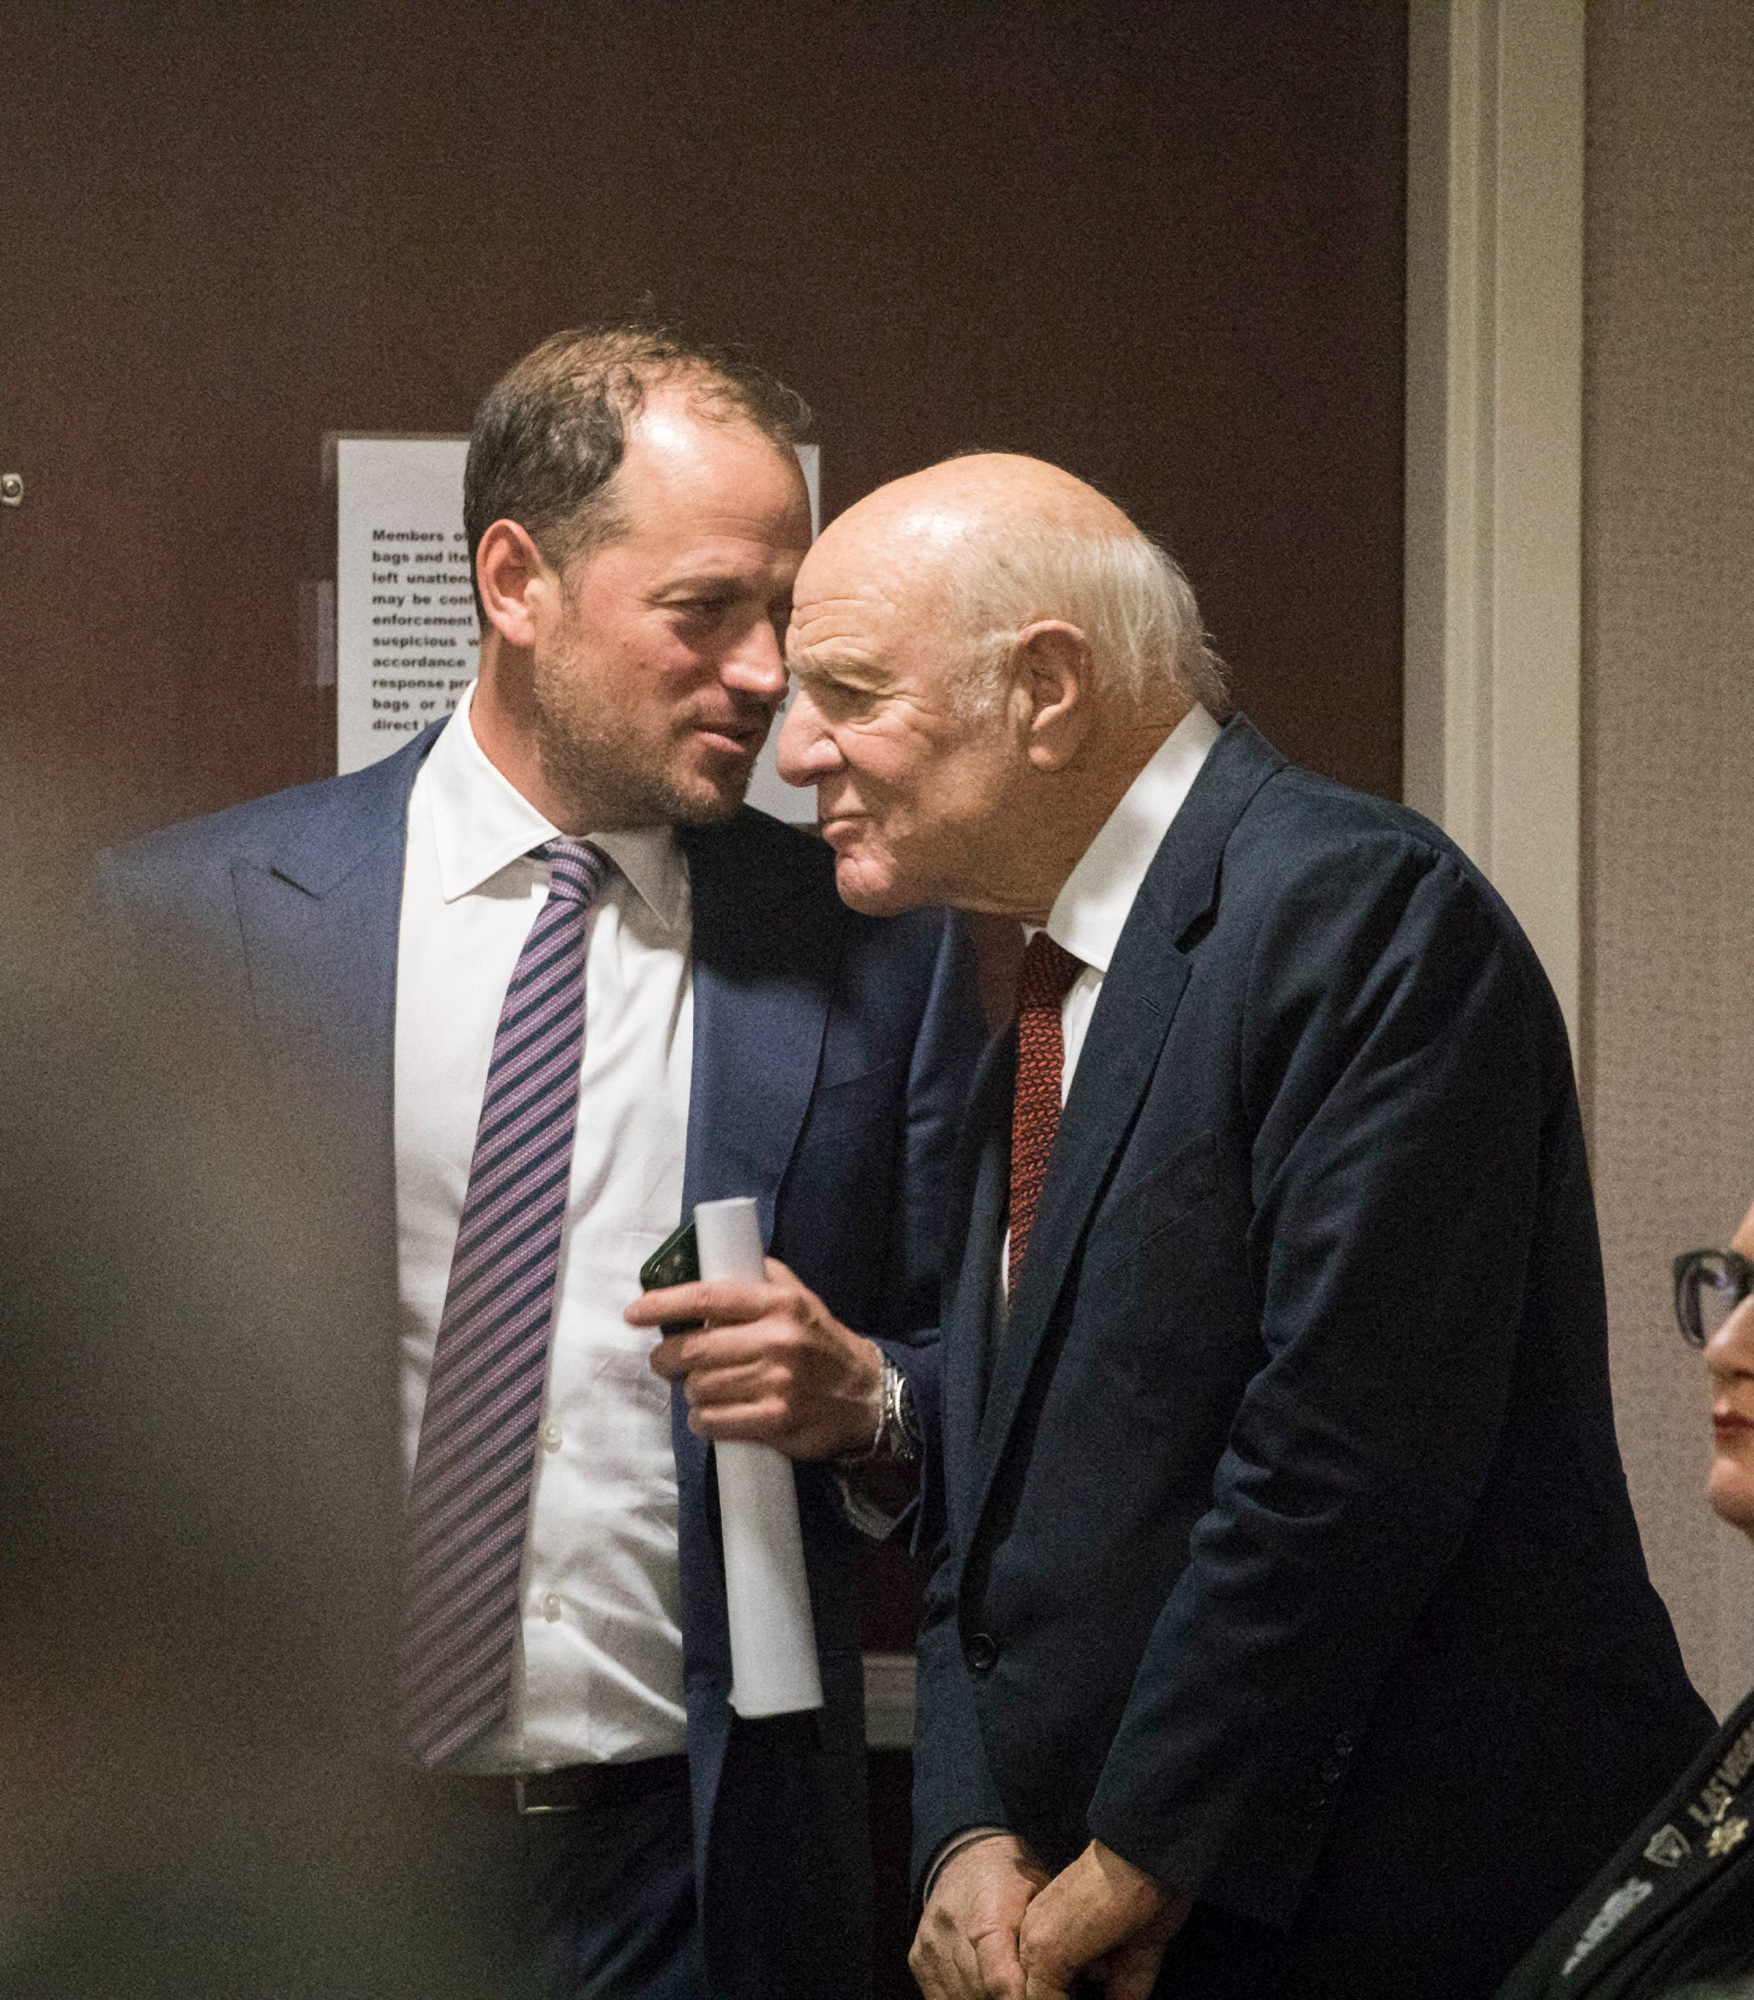
In a dramatic turn of events that sent ripples through the gaming and hospitality industries, billionaire media mogul Barry Diller formally withdrew his massive $18 billion bid to acquire MGM Resorts International. The announcement, made by the Strip casino giant on Wednesday, brought an end to months of intense speculation and high-stakes negotiation between the 84-year-old investor and the Las Vegas-based corporation’s board of directors. Diller, operating through his investment vehicle People Inc.—which already held a commanding 26 percent stake in MGM—had tabled a cash offer of $48.30 per share to capture the remaining 74 percent of the company. The sheer scale of the offer, coupled with Diller’s reputation as a shrewd and sometimes disruptive media executive, had positioned the deal as one of the most closely watched potential acquisitions in the recent history of the gaming sector. The abrupt termination of these talks signals not only a rejection of Diller’s valuation and strategic vision but also a firm declaration of independence from MGM’s leadership, who believe the company’s trajectory as a standalone entity holds far greater value than a buyout. The news effectively closes a chapter of uncertainty that has hung over MGM Resorts for the better part of the summer, and it positions the company to aggressively pivot back to its core operational expansions, particularly its digital footprint and its massive upcoming international development in Japan.
Paragraph 2: The Board’s Resolute Stand and Vision for a Standalone Future
Following the breaking news, MGM Resorts Chairman Paul Salem issued a brief but steadfast statement outlining the board’s collective decision to rebuff Diller’s overture. “The Board remains excited to continue to lead MGM Resorts as a standalone company,” Salem asserted, underscoring the management team’s confidence in its existing strategic roadmap. This confidence is not unfounded, as the board pointed to a multifaceted portfolio that remains unrivaled in the industry. MGM Resorts owns an impressive array of ten properties on the Las Vegas Strip, including iconic destinations such as the Bellagio, Aria, and Mandalay Bay, which continue to generate robust cash flow and attract high-end clientele. Beyond the domestic market, the company has cemented its reputation as a global gaming powerhouse through its operations in Macau, the world’s largest gambling hub, where it holds a significant presence. Furthermore, the board highlighted the company’s momentum in the digital betting sphere via BetMGM, a joint venture that has captured a substantial portion of the U.S. online sports betting and iGaming market. Perhaps most tantalizingly, the board referenced its ambitious future infrastructure, particularly the $10 billion integrated resort currently under construction in Osaka, Japan—a monumental project poised to open the country’s first casino resort and serve as a major catalyst for decades of future earnings growth. This comprehensive geographical and operational diversification, they argued, provides a superior risk-adjusted return profile that a private buyout could not replicate, convincing the special board committee that independence maximizes shareholder value.
Paragraph 3: The Anatomy of the Offer: Diller’s Digital Obsession
The road to this decisive moment was paved with rigorous due diligence and strategic deliberation. Salem confirmed that a special board committee had met extensively over the past several months with representatives from Diller’s People Inc. to negotiate the terms of the proposed buyout. However, the fundamental divergence arose from Diller’s primary motivation: the tech-savvy billionaire was laser-focused on capturing a commanding foothold in the company’s digital operations, particularly BetMGM. As the founder of IAC/InterActiveCorp—a holding company renowned for building and spinning off internet businesses like Expedia, Match.com, and Angi—Diller saw tangible synergy between his media and digital expertise and BetMGM’s explosive growth trajectory. His vision was likely to supercharge MGM’s online gaming unit, integrate it with his existing digital properties, and leverage data analytics to dominate the virtual gaming landscape. Yet, this digital-first focus did not necessarily align with the board’s valuation of its physical real estate assets, which command premium valuations in the tightly constrained Las Vegas land market. Diller’s offer of $48.30 per share was widely considered by analysts to be a slight discount to the sum-of-parts value of MGM’s real estate, its 56% stake in BetMGM, and its lucrative international licenses. This discrepancy between what Diller valued—the digital upside—and what the board valued—the combined physical and digital entity—created an insurmountable gap in the negotiation process, ultimately leading to the divergence in perspectives that killed the deal.
Paragraph 4: A Summer of Silence and Corporate Tension
Throughout the summer months, MGM Resorts executives maintained a studied silence regarding Diller’s overture, a strategy that frustrated analysts and investors alike who sought clarity on the company’s future. On the company’s quarterly earnings conference call in July, CEO Bill Hornbuckle conspicuously alluded to the existence of the board committee but deftly declined to entertain any questions pertaining to the Diller offer, citing the ongoing nature of the review. “I’m confident our board will pursue the course of action that’s in the best interest of the company and our shareholders,” Hornbuckle stated tersely at the time, a telling deflection that suggested a bitter internal struggle between a major shareholder wielding significant influence and a management team fiercely protective of its autonomy. Diller, with a net worth of approximately $5.7 billion according to Forbes, has methodically increased his ownership stake in MGM Resorts since 2020, gradually building his position to a level that allowed him to force a serious hearing for his acquisition proposal. The quiet tension likely boiled over during the recent board meetings where Diller pushed for a faster timeline to streamline the integration process. While Diller has no other gaming holdings in his portfolio, his media empire—spanning over 40 properties under the IAC umbrella—provided him with the financial firepower and the intellectual capital to challenge the status quo, making the board’s unanimous rejection a decisive victory for management over an activist-minded shareholder.
Paragraph 5: The Broader M&A Landscape and the Fertitta Comparison
The withdrawal of Diller’s offer cannot be viewed in isolation, as it coincides with a seismic wave of consolidation sweeping through the gaming industry. The proposal from Diller came exactly one week after rival Caesars Entertainment announced its own acquisition by billionaire Tilman Fertitta’s hospitality and entertainment company in a staggering $17.6 billion deal. On Tuesday, just one day before Diller’s withdrawal was made public, Caesars shareholders formally approved that transaction, signaling a clear appetite for big-ticket consolidation within the sector. The contrasting outcomes of these two major deals highlight a crucial divide in investor sentiment. Fertitta, who owns the Golden Nugget casinos and the Houston Rockets, successfully argued that scale and operational efficiency would allow Caesars to unlock hidden value, particularly through cost synergies and a diversified entertainment portfolio. In contrast, MGM’s board apparently argued that its existing standalone strategy—encompassing its premium Strip assets and its next-generation digital push—already promises superior organic growth without the burden of debt associated with a leveraged buyout. Furthermore, the market context plays a significant role; with Las Vegas tourism rebounding to record levels and international travel in Macau surging post-pandemic, MGM’s cash flow is more robust than ever. Board members likely calculated that retaining independence during this upswing would yield better long-term returns than accepting a cash premium now, effectively betting against the liquidity of a media investor who lacked deep integration experience in the highly regulated physical casino industry.
Paragraph 6: The Path Forward: Independence, BetMGM, and Diller’s Next Move
Moving forward, MGM Resorts now enters a new phase of strategic clarity, freed from the overhang of a potential takeover. The focus will immediately shift back to execution, with management needing to address the capital intensive nature of the Osaka build-out and the fiercely competitive race for market share in the digital betting space. The termination of the deal, however, does not remove Diller from the equation entirely. As the holder of a massive 26 percent stake, he remains the company’s largest shareholder and retains significant board influence, meaning he could easily revive his interest in the future or push for management changes if the stock price underperforms. Analysts anticipate that MGM stock may face slight downward pressure in the short-term as merger arbitrageurs unwind their positions, but the long-term narrative remains bullish given the company’s diversified asset base. For Diller, the withdrawal represents a rare public setback, though his track record suggests he is not one to abandon a profitable stake hastily; he may now pivot to simply holding his equity and observing how MGM executes its digital roadmap independently. Ultimately, while the blockbuster marriage of a digital media titan and a casino giant has been called off, the strategic realities that motivated it—the importance of online gaming and the consolidation of Strip assets—remain deeply entrenched. The Las Vegas landscape stands at a crossroads, and MGM Resorts has boldly chosen to build its own destiny rather than cede control to an external investor, a gamble that will now be judged by the fickle markets that never sleep.


